Services / Concentrated Stock & RSU Tax Planning
Concentrated Stock & RSU Tax PlanningA Tax Plan for Wealth Built in Company Stock
Years of RSU vesting can quietly turn one ticker into most of your net worth. We plan the tax side of that position: the withholding gap at each vest, the cost of unwinding it over several years, and what California can still tax after you move.
We explain the tax consequences of every path. Whether to buy, sell, or hold is your decision, and your financial advisor's.
22%
Flat federal withholding on most RSU vests, often below the rate you actually owe
37%
Mandatory federal withholding on supplemental wages above $1 million in a year
13.3%
California's top rate, which can still reach RSU income that vests after you move
10b5-1
A preset trading plan that can spread sales across tax years
Who This Is For
This service is built for senior tech professionals at public companies whose restricted stock units (RSUs: shares your employer grants that become yours as they vest) have grown into a large share of their net worth. It is built for directors and VPs in California, many of them weighing a move to Texas or Florida.
If your equity is a small part of your finances and your withholding covers your bill each year, you probably do not need this service. If you owed unexpectedly in April, hold a seven-figure position in one company, or are planning an exit or a move, this is where we start.
We design the tax outcome before the year closes, not after the 1099-B arrives.
Services
What We Plan For
Closing the Withholding Gap
RSU vest income is taxed as wages. Your employer usually withholds a flat 22% for federal tax, but if your marginal bracket is higher than that, every vest leaves a balance due. We project the gap before it arrives and set estimated payments so April is not a surprise. California also takes 1.3% of all wages for state disability insurance in 2026, with no cap, and RSU vests count as wages.
Unwinding a Concentrated Position Over Several Years
Selling a large position in one year can push the gain into the top brackets. We map the tax cost of spreading sales across several years, including lot selection, holding periods, and the 3.8% net investment income tax on gains after vesting.
California Sourcing When You Move
California can tax part of an RSU that vests after you leave, based on how many of your workdays between grant and vest were spent in California. We time the move around your vest schedule and document residency so the allocation holds up.
10b5-1 Trading Plans
Insiders often sell through a 10b5-1 plan: a written schedule adopted in advance, with a waiting period before the first trade. We model the tax result of the schedule you and your advisor are considering, so the sales land in the tax years you intend.
Getting the Cost Basis Right
Your cost basis in vested shares is their value on the vest date, because you already paid tax on that amount as wages. Brokers often report a zero or missing basis on Form 1099-B. We reconcile every lot so the same income is not taxed twice.
Stacking With Other Strategies
A large vest year can be paired with other moves: giving appreciated shares to charity, retirement plan contributions, or timing other income. We show how each one changes the tax result of the year, and who each one applies to.
Process
How the Work Runs
Equity Inventory
We gather your grant agreements, vest schedule, brokerage lots, and recent returns, and build a picture of every share you hold and every vest still coming.
Tax Projection
We project this year and the next several: the withholding gap on each vest, your bracket, and the tax cost of the sale paths you are considering.
Move and Residency Review
If you are leaving California, we map your workdays between grant and vest and show how the timing of the move changes what California can tax.
Written Strategy
You receive a written plan: the order of operations, the deadlines, the estimated payments, and the questions to settle with your financial advisor.
Implementation and Filing
We carry the plan onto your returns, including cost basis corrections and any part-year or nonresident California filing.
Quarterly Check-Ins
New grants, refreshes, and price moves change the picture. We revisit the plan through the year so the next vest is already accounted for.
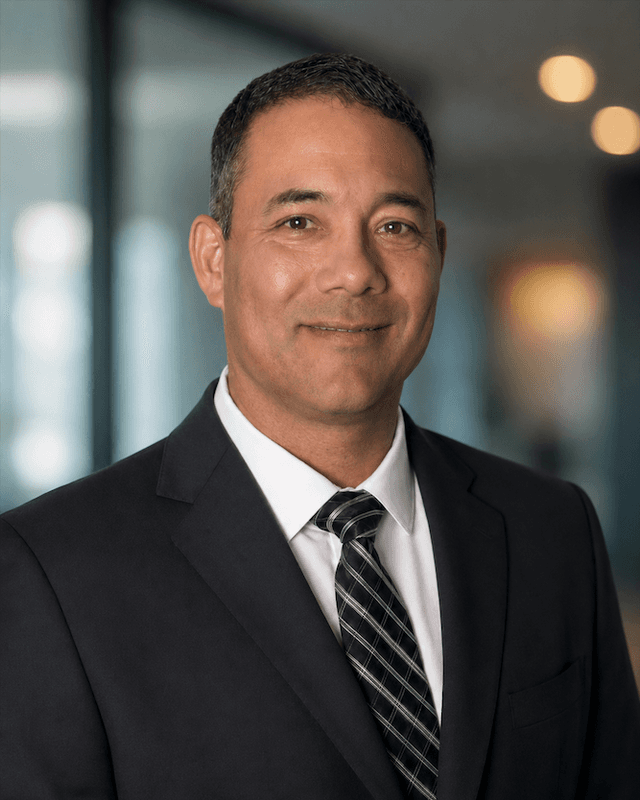
Meet Jesse Lipscomb
Founder and CEO, Roadmap Tax Services
Enrolled Agent | Series 65 Financial Advisor
Most tax firms file your return and disappear. Jesse built Roadmap Tax to do the opposite. With dual expertise in tax strategy and financial advisory, Jesse works with high-income earners and business owners year-round to find savings their previous CPA never looked for. His clients do not wonder if they are overpaying. They know exactly where their money is going, what strategies are working, and what is coming next. That is what happens when your tax professional actually knows you.
The Team
Your tax advisors
A dedicated team of Enrolled Agents working with you year-round.
Enrolled Agents are federally licensed tax specialists, the highest credential the IRS awards. They can represent clients before the IRS in audits, collections and appeals.
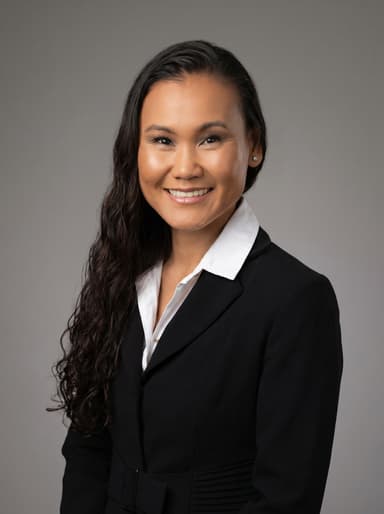
Sandy Kisner, EA
Tax Strategist
Sandy focuses on helping entrepreneurs and high-earning professionals reduce their tax burden and build long-term wealth. She works with small business owners, technology professionals, physicians, real estate investors, and brokers, delivering proactive tax planning tailored to each client. Clients rely on Sandy for clear guidance, creative problem-solving, and practical solutions that turn complex tax laws into real financial opportunities.
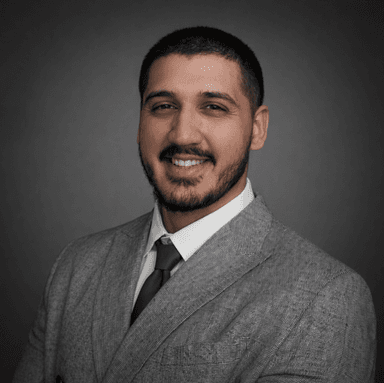
Alex Lazo, EA
Tax Strategist
Alex brings nearly five years of experience helping clients take control of their tax outcomes. A Point Loma Nazarene University accounting graduate, he specializes in proactive tax planning for equity-compensated professionals, real estate investors, and self-employed business owners. Originally from San Diego, Alex is known for making complex tax concepts accessible and actionable, helping clients use the tax code as a tool for building wealth.
Questions?
RSU Tax Planning FAQ
Why do I owe tax in April when my employer already withheld on my RSUs?
RSU vest income counts as wages, and employers usually withhold a flat 22% for federal tax on it (37% on supplemental wages above $1 million in a year). If your income puts you in a higher bracket, the withholding falls short and the difference is due when you file. Estimated payments during the year can close the gap before it becomes a balance due.
Will you tell me whether to sell my company stock?
No. We explain the tax consequences of selling, holding, or giving shares away, and how the timing changes the result. The decision about your investments belongs to you and your financial advisor. We work alongside advisors regularly and are glad to coordinate with yours.
If I move from California to Texas or Florida, will California still tax my RSUs?
Often, yes, for part of them. California generally sources RSU income by the share of your workdays between grant and vest that were spent working in California. An RSU granted while you lived in California and vesting after you move can still carry a California portion. Gains on shares you sell after you become a resident of another state are a different question, and residency documentation matters for both.
What is a 10b5-1 plan, and how does it affect my taxes?
A 10b5-1 plan is a written trading plan that company insiders adopt in advance, setting when and how many shares are sold. After a required waiting period, sales happen on schedule. For taxes, the plan decides which years the gains land in, so we model the schedule before it is adopted rather than after the trades run.
Are gains on shares I hold after vesting taxed the same way as the vest?
No. The value at vest is taxed as wages. Any change in value after vest is a capital gain or loss when you sell: short-term if you held the shares one year or less, long-term if longer. Gains on shares sold after vesting are investment income and can also be subject to the 3.8% net investment income tax. Wages never are.
Do you only work with tech employees in California?
Most of our RSU clients are senior tech professionals in California, and many are moving to Texas or Florida. We also work with equity holders in other states and with people who have already moved. Our offices are in San Diego, Frisco, Texas, and Panama City Beach, Florida.
Services
Related Services
Tax Strategy for High-Income Earners
The full plan your equity strategy sits inside, built on current law.
Retirement Tax Planning
Retirement contributions that can offset part of a large vest year.
Tax Strategy Subscription
Quarterly planning so each new grant and vest is accounted for before it lands.
Plan the Tax Side of Your Equity
Tell us about your grants, your vest schedule, and any move you are planning. We will follow up within one business day.
Two ways to start: a free 15-minute Discovery Call, or a $500 one-hour Tax Strategy Consultation. Both start with the contact form. Ongoing work runs through our Tax Strategy Subscription, starting at $300 a month plus a $3,000 setup fee.